Chapter – 1.
Recording
of Transactions – II (Special Purpose Books)
1.1
Need & Classification of Special Journals
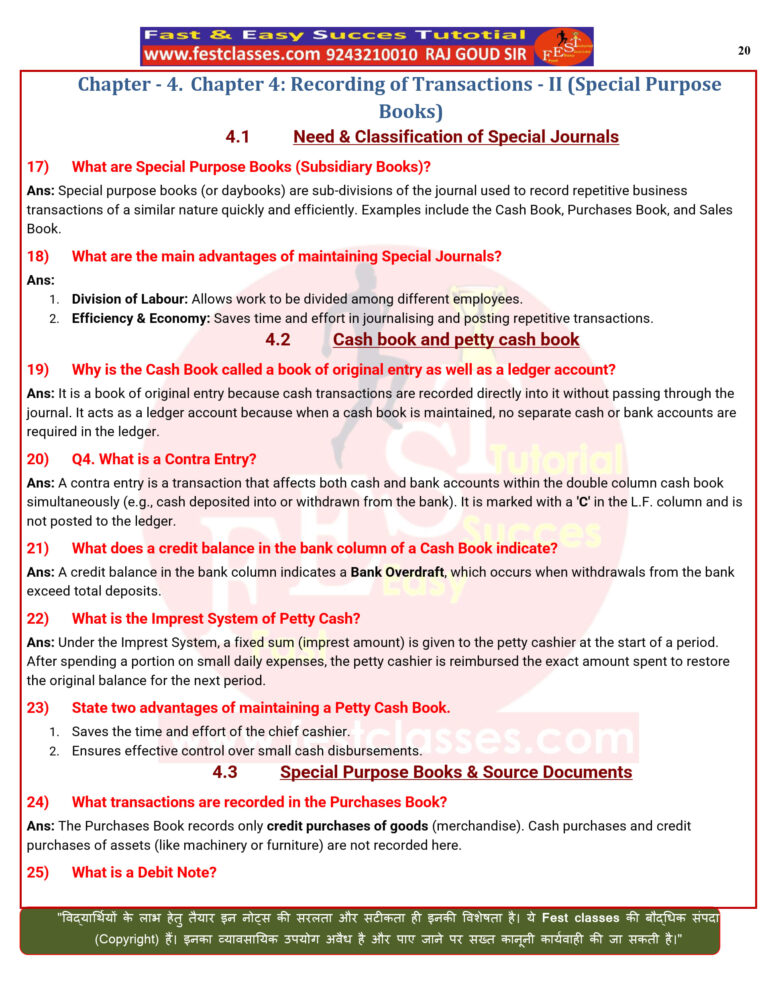
1) What
are Special Purpose Books (Subsidiary Books)?
Ans: Special purpose books (or daybooks) are sub-divisions
of the journal used to record repetitive business transactions of a similar
nature quickly and efficiently. Examples include the Cash Book, Purchases Book,
and Sales Book.
2) What
are the main advantages of maintaining Special Journals?
Ans:
- Division of Labour: Allows work to be divided among different
employees. - Efficiency & Economy: Saves time and effort in journalising and
posting repetitive transactions.
1.2
Cash book and petty cash book
3) Why
is the Cash Book called a book of original entry as well as a ledger account?
Ans: It is a book of original entry because cash
transactions are recorded directly into it without passing through the journal.
It acts as a ledger account because when a cash book is maintained, no separate
cash or bank accounts are required in the ledger.
4) Q4.
What is a Contra Entry?
Ans: A contra entry is a transaction that affects both
cash and bank accounts within the double column cash book simultaneously (e.g.,
cash deposited into or withdrawn from the bank). It is marked with a ‘C’
in the L.F. column and is not posted to the ledger.
5) What
does a credit balance in the bank column of a Cash Book indicate?
Ans: A credit balance in the bank column indicates a Bank
Overdraft, which occurs when withdrawals from the bank exceed total
deposits.
6) What
is the Imprest System of Petty Cash?
Ans: Under the Imprest System, a fixed sum (imprest
amount) is given to the petty cashier at the start of a period. After spending
a portion on small daily expenses, the petty cashier is reimbursed the exact
amount spent to restore the original balance for the next period.
7) State
two advantages of maintaining a Petty Cash Book.
- Saves the time and effort of the chief cashier.
- Ensures effective control over small cash disbursements.
1.3
Special Purpose Books & Source Documents
8) What
transactions are recorded in the Purchases Book?
Ans: The Purchases Book records only credit purchases
of goods (merchandise). Cash purchases and credit purchases of assets (like
machinery or furniture) are not recorded here.
9) What
is a Debit Note?
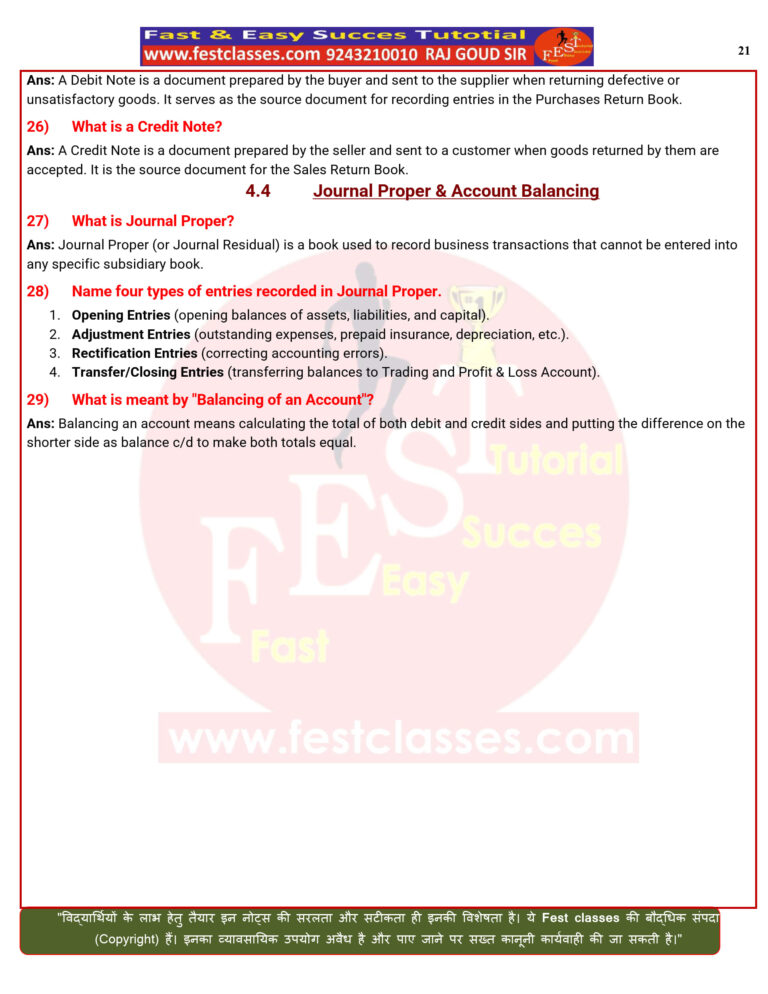
Ans: A Debit Note is a document prepared by the buyer and
sent to the supplier when returning defective or unsatisfactory goods. It
serves as the source document for recording entries in the Purchases Return
Book.
10)
What is a Credit Note?
Ans: A Credit Note is a document prepared by the seller
and sent to a customer when goods returned by them are accepted. It is the
source document for the Sales Return Book.
1.4
Journal Proper & Account Balancing
11)
What is Journal Proper?
Ans: Journal Proper (or Journal Residual) is a book used
to record business transactions that cannot be entered into any specific
subsidiary book.
12)
Name four types of entries recorded in Journal
Proper.
- Opening Entries (opening balances of assets, liabilities, and
capital). - Adjustment Entries (outstanding expenses, prepaid insurance,
depreciation, etc.). - Rectification Entries (correcting accounting errors).
- Transfer/Closing Entries (transferring balances to Trading and Profit
& Loss Account).
13)
What is meant by “Balancing of an
Account”?
Ans: Balancing an account means calculating the total
of both debit and credit sides and putting the difference on the shorter side
as balance c/d to make both totals equal.